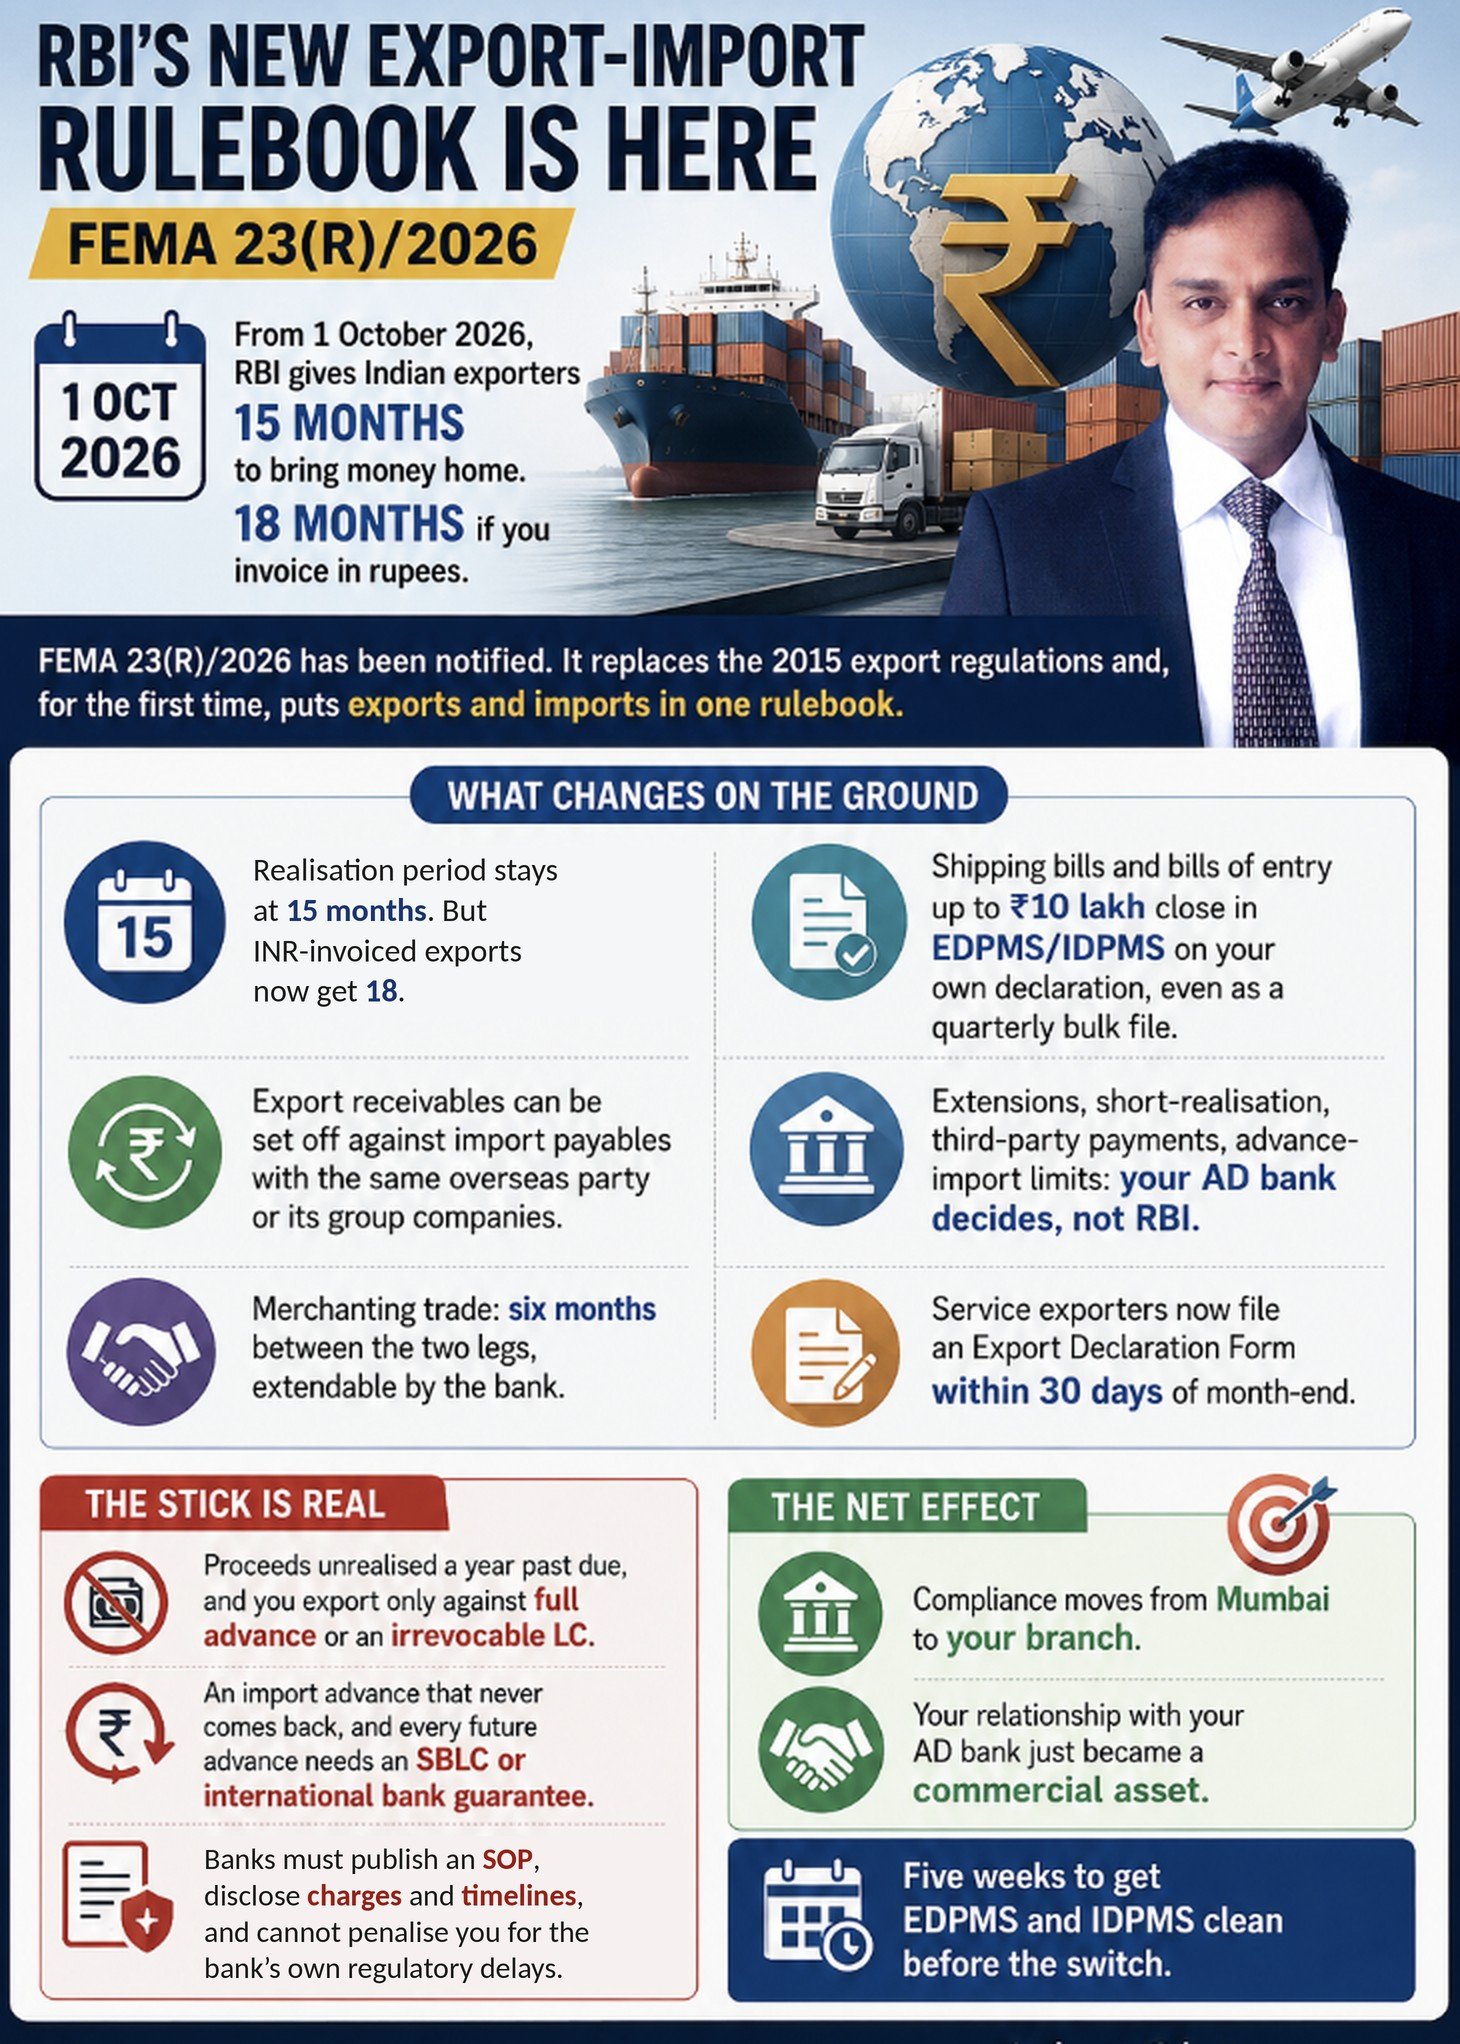
The FEMA 2026 export rule change in India takes effect on 01-10-2026. On that date the Reserve Bank of India’s Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 — Notification No. FEMA 23(R)/2026-RB, dated 13-01-2026 and gazetted 15-01-2026 — replace the 2015 regulations that have governed how every Indian exporter gets paid for the past decade.
This is not a tidying-up exercise. The RBI has deleted most of its own numeric prescriptions from the export rules and handed the judgement to your bank. The practical effect for an Indian exporter is that from 1 October your Authorised Dealer bank’s internal policy becomes the rulebook you actually live under — and every bank’s will be slightly different.
Two of the changes carry real commercial teeth: an eighteen-month realisation window for rupee-invoiced exports, and a self-executing restriction on any exporter carrying receivables more than a year overdue. Here is the full export-side picture, who gains, who should be nervous, and what to do in the five weeks that are left.
The FEMA 2026 export rule change in one sentence
The RBI has stepped back and the Authorised Dealer bank has stepped forward. Where the old regime set fixed ceilings — a cap on how much invoice value you could reduce, a fixed percentage you could self write off — the 2026 regulations mostly say “the Authorised Dealer may permit, on being satisfied as to the reasons cited”. Discretion replaces the ceiling. That is a large deregulation for exporters who bank well, and a new source of friction for exporters who do not.
The seven export changes that matter
1. Realisation: 15 months, and 18 months if you invoice in rupees
Regulation 5 fixes the realisation and repatriation period at fifteen months from the date of shipment for goods, and from the date of invoice for services. Goods sent to an overseas warehouse get fifteen months from the date of sale out of that warehouse. Project exports run to the payment terms of the contract.
The genuinely new number is the proviso: where the export is invoiced or settled in Indian Rupees, the period is eighteen months. That is three extra months of working-capital headroom, available only to exporters willing to price in INR. If a buyer in the Gulf, Sri Lanka, Bangladesh, Russia or Mauritius has asked you to settle in rupees and you have hesitated, the arithmetic just moved.
Extensions beyond fifteen or eighteen months no longer travel to the RBI. Your AD bank may grant them on request, if satisfied with the reasons cited — which makes the quality of your banking relationship a commercial variable in a way it was not before.
2. The ₹10 lakh self-declaration — the single biggest administrative relief
Regulation 4(2) is the clause that will clear years of accumulated clutter off Indian exporters’ books. Where the shipping bill for goods, or the invoice for services, is up to ₹10 lakh or its foreign-currency equivalent, the EDPMS entry may be closed on a declaration from the exporter that payment against the shipping bill has been realised in full or otherwise. Better still, that declaration may be submitted on a quarterly basis, in bulk, rather than bill by bill.
If you run a high-volume, low-ticket export book — samples, e-commerce parcels, courier shipments, spare parts, small trial orders — this is the clause that matters most to you. Thousands of individually trivial open entries become one quarterly declaration.
3. Reduction in export value — the percentage caps are gone
Regulation 6 lets an AD bank permit a reduction in the invoice value on the exporter’s request, where it is satisfied with the reasons cited. There is no percentage ceiling written into the regulation. And where export value is up to ₹10 lakh per shipping bill or invoice, a reduction — including full non-realisation — may be permitted on a declaration from the exporter alone.
The percentage-based reduction ceilings and the self write-off allowances that exporters memorised under the old regime do not appear in the new text. A threshold and a declaration take their place. Two cautions: this is a banker’s discretion, not a right, and a write-down of export value has downstream GST and duty drawback consequences — model those before you use it at scale.
4. Set-off against import payables gets materially wider
Regulation 7 lets an AD bank allow export receivables to be set off against import payables to or from the same overseas buyer or supplier, or with that party’s overseas group or associate companies, within the stipulated period for realisation or any extension allowed. The same-calendar-year constraint and the requirement for a pre-existing written agreement that characterised the old regime do not appear in the new text.
For any Indian exporter that also buys from the same multinational group — extremely common in chemicals, auto components, textiles, engineering goods and electronics — this removes a real cash-flow drag.
5. Third-party receipts are now normal, not exceptional
Regulation 8 permits an AD bank to allow third parties — other than the parties actually undertaking the export and import — to receive and make payments for export transactions, subject to the bank being satisfied as to the bona fides. This legitimises the payment-agent and group-treasury structures that many Gulf and Southeast Asian buyers already use, and which previously forced Indian exporters into awkward workarounds or lost the order.
6. Services and software exporters get a cleaner EDF regime
Under Regulation 3(2), an exporter of services files the Export Declaration Form within 30 days from the end of the month in which the invoice was raised. An exporter serving one or more recipients in a month may file a single consolidated EDF for all of those exports. Services other than software may file on or before the date of receipt of payment, and the AD bank may extend the filing period on a reasoned request.
For software, the specified authority under Regulation 2(1)(f) is an Authorised Dealer or Software Technology Parks of India in the domestic tariff area, and the Development Commissioner in an SEZ. For IT services, design, consulting and SaaS exporters billing dozens of small overseas invoices a month, one EDF instead of dozens is a meaningful reduction in work.
7. Advance receipts must run through one bank
Regulation 10(1) requires that where an exporter receives an advance, the advance amount and the realisation of export proceeds are routed through the same Authorised Dealer — unless the exporter intimates the change to both banks. Multi-bank exporters should map this before October rather than discover it at the counter.
Regulation 10(4) is a reminder rather than a change: interest on an advance payment received for exports must stay within the all-in-cost ceiling under the Foreign Exchange Management (Borrowing and Lending) Regulations, 2018.
Regulation 13: the export rule change with teeth
Everything above is relief. This one is not. Read it twice.
If export proceeds remain unrealised for a period beyond one year from the due date of realisation or the extended period, the exporter shall undertake further exports only against receipt of full advance or an irrevocable letter of credit.
That is a commercial handcuff, and it attaches by operation of the regulation itself — there is no list to be placed on, no notice, no hearing. An exporter carrying stale EDPMS entries from 2023 and 2024 can find, on 1 October, that its bank will only process new shipments against advance payment or a confirmed LC.
Consider what that means commercially. Very few overseas buyers will pay 100 per cent in advance to a supplier they have been buying from on open account or documents-against-payment terms. An irrevocable LC costs the buyer money and takes weeks to arrange. In practice, a Regulation 13 restriction does not slow an export book down — it stops it, and it stops it at precisely the moment when the exporter is already short of cash because old receivables have not come in.
The good news is that the RBI has supplied the tools to avoid it in the same notification. The ₹10 lakh bulk-closure route in Regulation 4(2), the extension route in Regulation 5 and the write-down route in Regulation 6 all exist so that you can clear those entries. The window to use them is now. Doing it in November, after a bank has already restricted you, is a much harder conversation — and one you will be having from a weaker position.
What the new export reporting rules require
Regulation 18 sets the reporting machinery behind all of the above. Your AD bank must enter EDF details in EDPMS within five working days of receiving them, enter all inward and outward remittances for exports, imports and merchanting trade, and monitor every transaction for closure — following up with you for the documents. It marks off the EDPMS entry once export value has been realised.
Two exporter-friendly discretions sit inside Regulation 18. The bank may, on your request and citing reasons, close an entry relating to an export advance where no export has been made and refund of the advance is not possible, once satisfied as to genuineness. And all foreign trade transactions are reported by the bank in FETERS.
The practical point: EDPMS is not a passive record. From October it is the mechanism that triggers Regulation 13. Whatever is sitting in it on 1 October is what your bank will act on.
Project exporters and merchanting traders
Project exports (Regulation 15) get a workable framework. The AD bank may permit receipts and payments as per the underlying contract once satisfied as to the genuineness of the project. And subject to bank monitoring, a project exporter may deploy temporary cash surplus generated outside India in short-term instruments with an original or residual maturity of up to one year — including treasury bills and deposits with banks outside India. For EPC contractors running long overseas projects, that is real treasury flexibility.
Merchanting trade (Regulation 16) keeps one hard number: the period between the outward remittance and the inward remittance, or vice versa, must not exceed six months, extendable by the AD bank on a reasoned request. Outward remittances are sent only after inward remittances are received from the overseas buyer — though the bank may, on request, allow receipt from or payment to a third party. Documents evidencing both legs go to the bank, which closes or updates entries in both EDPMS and IDPMS.
Several conditions from the old merchanting-trade framework — an overall completion timeline, the requirement that the transaction be profitable, and the restriction on agency commission — do not appear in the new text. For Indian trading houses running third-country trade through Dubai, Singapore or Hong Kong that is a more workable framework, but confirm your position with your bank: RBI Master Direction guidance operationalising these regulations was still awaited at the time of writing.
If you also import: three clauses to check
Most Indian exporters import something — raw material, components, capital equipment. The same notification changes the import side, and two of those changes can bite an exporter’s cash position just as hard as Regulation 13.
- Regulation 9 — your contract is now the deadline. The RBI has stopped prescribing a period for import payment altogether. The bank monitors IDPMS and follows up for payment within the period specified in the underlying contract. A vague or missing payment-terms clause used to be survivable because the regulation supplied a default; now the bank looks to your contract and finds nothing to monitor against. Audit your import contracts.
- Regulation 10(3) — your bank sets the advance threshold. The fixed dollar ceilings above which advance import remittance needed a standby LC are gone. Each AD bank may now consider specifying its own thresholds, after satisfying itself the requirement is genuine. Ask your relationship manager for the number in writing before you agree advance terms with a supplier.
- Regulation 12 — the importer’s Regulation 13. If the import does not materialise, the advance must be repatriated. If it is not, or the IDPMS entry has not been marked off, any future advance payment for imports requires an unconditional, irrevocable standby letter of credit or guarantee from an international bank of repute, or from an AD bank in India counter-guaranteed by one. Standby LCs are neither cheap nor instant.
Regulation 11 also permits an AD bank to allow advance remittance for the import of gold and silver, notwithstanding the general provisions — directly relevant to jewellery manufacturers and bullion importers. And the ₹10 lakh declaration and quarterly bulk-closure mechanism in Regulation 4(2) applies to IDPMS entries exactly as it does to EDPMS.
The clause nobody is talking about: Regulation 19
If discretion is moving to banks, the counterweight is that banks must now be transparent about how they use it. Regulation 19 requires every AD bank to put in place a separate, comprehensive, well-documented internal policy and SOP covering, at minimum: the list of documents, timelines and charges for each process and approval; extension of the time period for export realisation and repatriation; adjustment of export proceeds, including under- and non-realisation; advance receipts for exports; delegation of powers for internal approvals; and export factoring.
Three sub-clauses deserve to be printed out and kept in a drawer:
- The policy must include a grievance escalation and appeal mechanism, with the appeal heard at a higher internal level than the original decision.
- Charges must be reasonable and proportional to the services rendered.
- The bank shall not levy any charges or penalty on its constituent — exporter, importer or merchant trader — for any regulatory delay or violation by the bank itself.
And critically, Regulation 19(4): the bank must disclose its policy and the main features of its SOP on its website. From 1 October an Indian exporter can, for the first time, compare Authorised Dealers on published trade-finance turnaround times and charges — and move the business accordingly. In a regime built on banker’s discretion, that disclosure is the exporter’s main piece of leverage. Use it.
Which Indian exporters gain, and which should be nervous
| Exporter profile | Net effect from 01-10-2026 |
|---|---|
| Established exporter, clean EDPMS, good bank relationship | Clear gain. Faster extensions, wider set-off, bulk closure of small entries, no RBI referral. |
| High-volume, low-ticket exporter (samples, e-commerce, courier) | Largest gain. The ₹10 lakh declaration and quarterly bulk closure removes most of the reconciliation burden. |
| Services, software and SaaS exporter | Gain. Single consolidated monthly EDF, 30-day filing window from month-end. |
| Exporter selling into rupee-settlement corridors | Gain. Eighteen months instead of fifteen is three months of free working capital. |
| Project exporter / EPC contractor | Gain. Contract-based receipts plus overseas deployment of temporary cash surplus up to one year. |
| Exporter with receivables overdue more than a year | At risk. Regulation 13 restricts you to full advance or an irrevocable LC. Clean up before October. |
| Exporter who also imports, with open IDPMS advances | At risk. Regulation 12 forces a standby LC or guarantee on all future advances. |
| First-time or small exporter without a banking track record | Mixed. Discretion cuts both ways; outcomes now depend on which bank you use. |
| Merchanting trader | Gain, with caution. Fewer prescriptive conditions, but the six-month leg-to-leg limit is firm. |
What the FEMA 2026 export rule change does not touch
These are FEMA regulations governing payments. They do not touch DGFT policy, customs, GST or tariffs. In particular:
- RoDTEP is notified only up to 30-09-2026 — a separate deadline landing the day before the FEMA 2026 export rules start. Watch for the extension notification; do not assume the two are connected.
- IGST refunds and duty drawback still hinge on proof of realisation. A Regulation 6 write-down of export value has downstream GST and drawback consequences — take advice before using it at scale.
- Certificates of origin are issued only through trade.gov.in, with the invoice number matching the shipping bill.
- Tariffs are unchanged by this notification. The India–UK CETA has been in force since 15-07-2026; the India–EU agreement is concluded but not yet in force; there is no India–US free trade agreement. See our trade agreements and tariffs page.
- Your IEC and DGFT registrations are unaffected — see our guides to IEC registration and DGFT schemes.
Your 30-day export compliance checklist before 01-10-2026
- Pull your full EDPMS outstanding report from your AD bank. Not a summary — the line-item list with shipping bill dates and due dates. Pull IDPMS too if you import.
- Flag every entry more than a year past its due date. This is your Regulation 13 exposure and it is the only item on this list that can stop your business. Everything else is secondary.
- Bulk-close everything under ₹10 lakh using the Regulation 4(2) declaration route as soon as your bank operationalises it.
- Decide, entry by entry, on the larger overdue items — chase, extend under Regulation 5, or reduce under Regulation 6. Model the GST and drawback impact before you write anything down.
- Ask your AD bank for its FEMA 2026 policy and SOP in writing — its extension turnaround time, its charge schedule, and, if you import, its advance-remittance threshold.
- Compare at least two banks. The SOPs must be published from October. If yours is slow or expensive, this is the moment leverage exists.
- Map advance receipts to a single AD bank per Regulation 10(1), or file the intimations with both banks.
- Model your INR-invoicing option. Eighteen months instead of fifteen is real working capital — decide which buyers and which corridors it suits.
- Audit every import contract for an explicit payment-terms clause. Under Regulation 9 that clause is now the deadline your bank enforces.
- Brief your finance and documentation team. A lot of 2015 muscle memory is now wrong, and the people filing your EDFs are the ones who need to know first.
How OZIANT and ZJELL help
Cross-border B2B trade with India fails on documentation far more often than it fails on product. The FEMA 2026 export rule change moves a large part of that documentation burden from a published rulebook to a negotiation with your bank — exactly the kind of work most exporters are least equipped to do alone, and on a five-week clock.
- EDPMS and IDPMS clean-up before October. Our team works through your outstanding report line by line, sorts entries into close, extend or reduce, and prepares the declarations and covering letters your AD bank will accept.
- Regulation 13 exposure assessment. A single view of every receivable approaching or past the one-year mark, and what it will take to clear each one before the deadline.
- AD bank SOP comparison. We read the published policies of the major Authorised Dealers against your actual trade pattern and tell you, in numbers, what switching or renegotiating is worth.
- Contract clauses that survive the new rules. Payment terms, Incoterms and LC wording drafted so your bank has something enforceable to monitor — see our guides to Incoterms 2020 and letters of credit.
- Compliance-included sourcing for overseas buyers. Every supplier in the OZIANT verified network and our manufacturer directory is vetted before it reaches you, and documentation is handled single-window.
- Export management for Indian manufacturers — buyer identification, DGFT and FEMA compliance, and payment structuring — through ZJELL Limited, our export consulting arm. Our analysis of the US$220 million silver jewellery buyer gap shows how that work runs in practice.
If you are an overseas buyer, post an RFQ and we will come back with compliance-ready quotes. If you are an Indian exporter with an EDPMS backlog and five weeks on the clock, talk to our team — that conversation is materially cheaper before 1 October than after it.
Frequently asked questions
When does the FEMA 2026 export rule change take effect in India?
On 01-10-2026. The notification, FEMA 23(R)/2026-RB, is dated 13-01-2026 and was gazetted on 15-01-2026, but nothing changes operationally until 1 October. Things done or omitted to be done under the 2015 regulations before that date are protected by the supersession clause.
What is the new export realisation period under FEMA 2026?
Fifteen months from the date of shipment for goods and from the date of invoice for services. The new element is eighteen months where the export is invoiced or settled in Indian Rupees. Project exports follow the payment terms in the contract, and the AD bank can extend any of these on a reasoned request without a reference to the RBI.
Can Indian exporters still write off unrealised export bills?
The percentage-based self write-off allowances of the old regime do not appear in the 2026 regulations. Instead, Regulation 6 lets the AD bank permit a reduction in export value on request, and for bills up to ₹10 lakh a reduction including full non-realisation can be permitted on the exporter’s declaration alone. Detailed operational guidance from the RBI and from individual banks is still awaited.
What happens if my export proceeds are overdue by more than a year?
Under Regulation 13, if proceeds remain unrealised for a period beyond one year from the due date of realisation or the extended period, you may undertake further exports only against receipt of full advance or an irrevocable letter of credit. It applies by operation of the regulation, with no notice or hearing, which is why clearing or formally extending old entries before 01-10-2026 matters so much.
Do I have to file an EDF for every service export invoice?
No. Under Regulation 3(2) a services exporter files the EDF within 30 days from the end of the month in which the invoice was raised, and an exporter serving one or more recipients in a month may submit a single consolidated EDF covering all of those exports.
Does the FEMA 2026 export rule change affect my GST refund or duty drawback?
Not directly — these are FEMA regulations on payments, not tax rules. But because IGST refunds and duty drawback are tied to realisation of export proceeds, using Regulation 6 to reduce or write down export value can have tax consequences. Take specific advice before doing it at scale.
About this analysis. Based on the text of Notification No. FEMA 23(R)/2026-RB dated 13-01-2026, published in the Gazette of India Extraordinary Part III, Section 4 on 15-01-2026, signed by N. Senthil Kumar, Chief General Manager, Reserve Bank of India. Where we note that a provision from the 2015 regime is absent from the new text, that reflects the regulations as notified; RBI Master Directions and A.P. (DIR Series) circulars operationalising these regulations were still awaited at the time of writing on 28-08-2026, and individual AD bank policies will vary. This article is general information, not legal, tax or financial advice. Confirm your specific position with your Authorised Dealer bank and your own advisers before acting.